Work record
Ernst & Ernst v. Hochfelder
1976 · Postwar Contemporary · Court Decision · English
Abstract
Question Presented. Can investors recover money damages from an accounting firm under the federal antifraud rule when they claim only that the firm audited carelessly, not that it meant to deceive anyone?
Arguments. Customers who lost savings to a broker's sham escrow accounts, backed by the SEC, contended that the rule speaks of any practice operating as a fraud and that remedial laws deserve generous reading. The auditors replied that Congress chose words describing deliberate schemes and wrote negligence remedies only into narrower provisions carrying their own safeguards.
Holding. By six votes to two, the justices reversed the Seventh Circuit. Powell's opinion relied on ordinary and technical meanings of statutory terms, drafting history and the architecture of the 1933 and 1934 Acts, adding that an agency rule cannot outrun its enabling statute. Blackmun and Brennan saw no reason to separate careless harm from intended harm and stressed auditors' public responsibilities.
Why it matters for advisers. Since this decision, private plaintiffs alleging fraud under Rule 10b-5 against advisers, brokers or other market professionals must prove scienter, an intent to deceive or at least recklessness under later lower-court rulings. Ordinary negligence claims proceed under other provisions or state law instead.
Significance. The scienter element shaped decades of later litigation and was carried into SEC enforcement by Aaron in 1980.
Key figures
- Ernst & Ernst: Auditors of a Chicago brokerage for over two decades
- Leston B. Nay: Brokerage president behind the fictitious escrow accounts
- Lewis F. Powell Jr.: Wrote that the statute's vocabulary denotes intentional wrongdoing
- Harry A. Blackmun: Dissenter, with Brennan, for liability based on negligence
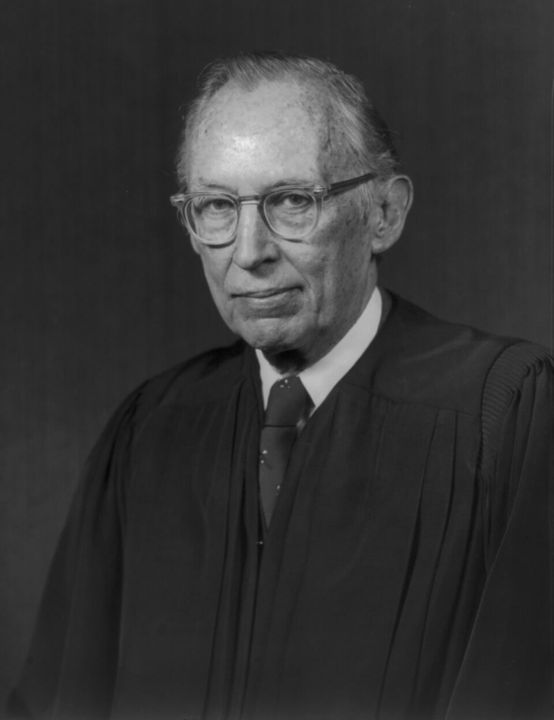

Summary
Ernst & Ernst, an accounting firm, audited First Securities Company of Chicago, a small brokerage house, from 1946 through 1967 and prepared the annual reports the firm filed with the Securities and Exchange Commission. Leston B. Nay, the brokerage's president and owner of 92 percent of its stock, persuaded certain customers to put money into special escrow accounts that he said would pay a high return. No such accounts existed; Nay took the funds for himself, and the transactions never appeared on the firm's books. The scheme came to light in 1968, after Nay's death, when he left a note calling the accounts spurious. The defrauded customers sued Ernst & Ernst under Section 10(b) of the Securities Exchange Act of 1934 and Rule 10b-5, claiming that a proper audit would have uncovered Nay's rule that only he could open mail addressed to him, and that disclosure of this irregular practice would have exposed the fraud. They expressly disclaimed any charge that the accountants acted intentionally; their claim rested on negligence. The District Court granted summary judgment for Ernst & Ernst, and the Seventh Circuit reversed. The question was whether a private suit for damages under Section 10(b) and Rule 10b-5 can succeed without proof of scienter, an intent to deceive, manipulate or defraud. The customers, supported by the SEC as amicus curiae, argued that the statute is remedial, that Rule 10b-5's language reaches any act that operates as a fraud, and that investors suffer the same loss from careless conduct as from deliberate deceit. Ernst & Ernst answered that the words of the statute describe intentional wrongdoing and that Congress set out negligence liability only in specific, limited provisions. On 30 March 1976 the Court reversed, six to two, with Justice Stevens not participating. Justice Powell reasoned that the words manipulative, device and contrivance are the vocabulary of knowing or intentional misconduct; that the legislative history described Section 10(b) as a catchall against new manipulative practices; that where Congress allowed recovery for negligence in the 1933 and 1934 Acts it did so expressly and with procedural limits; and that a Commission rule cannot reach further than the statute it implements. He declined to remand for trial on a new theory because the plaintiffs had always proceeded on negligence alone. Justice Blackmun, joined by Justice Brennan, dissented. He doubted the majority's reading, argued that an investor is injured as much by negligence as by deception, stressed the public role of the certifying accountant, and suggested Congress would have to act if such investors were to recover. The library text contains both opinions; most notes are left out, though several explanatory notes from the source appear after the dissent. Powell reserved in a footnote whether recklessness might satisfy the scienter requirement, and the courts of appeals later generally held that it can. Aaron v. SEC (1980) applied the same scienter rule to SEC enforcement suits under Section 10(b).
Virtues in this work
- Prudence: Powell refuses to extend a criminal and civil antifraud statute beyond the conduct its words describe, leaving broader liability to Congress.
- Justice: Blackmun insists that investors who lost their savings deserve a remedy against professionals whose certificates the public relies on.
- Industry: The case turns on what diligent auditing requires, and Blackmun's dissent treats careful inquiry by accountants as a duty owed to the public.
Plot or Argument
- Nay's escrow scheme and the mail rule
Powell sets out the brokerage president's fictitious escrow accounts, the customers' theory that Ernst & Ernst negligently failed to detect the rule that only Nay could open his mail, and their express disclaimer of any intentional wrongdoing by the auditors.
- The language of Section 10(b)
The statute speaks of manipulative or deceptive devices and contrivances. Powell reads these terms, especially manipulative, a term of art in securities markets, as describing intentional or knowing misconduct, and rejects the Commission's argument that the effect on investors rather than the actor's state of mind should control.
- Legislative history
Tracing the bills that became the 1934 Act, Powell finds Section 10(b) described as a catchall clause to deal with new manipulative or cunning devices, and finds nothing suggesting that Congress meant to reach mere negligence.
- The structure of the securities acts
Where Congress created express civil remedies, it specified whether liability required intent, negligence or no fault, and it attached procedural limits to negligence-based claims. Reading Section 10(b) to cover negligence would let plaintiffs bypass those limits.
- The reach of Rule 10b-5
Although parts of the rule's wording could be read to reach negligent conduct, the rule cannot exceed the power Congress granted the Commission in Section 10(b). The Court declines to remand, since the respondents had relied only on negligence throughout.
- Blackmun's dissent
Blackmun reads the rule as plainly covering negligent omissions, notes that the Second Circuit allowed negligence in SEC injunction suits, insists that the meaning of a violation should not depend on who sues, and emphasizes that the certifying accountant's duty runs to the public.
Characters
- Ernst & Ernst, petitioner
National accounting firm that audited First Securities Company of Chicago for more than twenty years.
- Hochfelder and other First Securities customers, respondents
Investors who lost money in Nay's fictitious escrow accounts and sued the auditors for negligence under Rule 10b-5.
- Leston B. Nay, president of First Securities
Brokerage president who ran the escrow fraud and kept his mail closed to others.
- Justice Lewis F. Powell Jr., author of the opinion of the Court
Held that a private Section 10(b) damages action requires scienter, not mere negligence.
- Justice Harry A. Blackmun, dissenter
Argued, with Justice Brennan, that negligence by a certifying accountant can violate Rule 10b-5.
Lessons
Intent as an element of securities fraud
The Court held that a private plaintiff suing under Section 10(b) must prove scienter, an intent to deceive, manipulate or defraud. Careless auditing, however costly to investors, is not by itself the kind of deceptive device the statute forbids.
- What did the respondents concede about Ernst & Ernst's state of mind, and why did that concession matter?
- What does Powell mean by calling manipulative a term of art?
- Should the law distinguish between losses caused by carelessness and losses caused by deliberate deceit?
Reading a statute through its words, history and structure
Powell's opinion uses three tools in turn: the ordinary and technical meaning of the statute's words, the drafting history of the 1934 Act, and a comparison with sections where Congress expressly allowed negligence claims. The opinion is a model of building an interpretive argument from several independent supports.
- Which of Powell's three lines of argument seems strongest, and why?
- How does the comparison with Sections 11 and 12 of the 1933 Act support the Court's conclusion?
- Can an agency's rule ever reach further than the statute that authorizes it?
The auditor's public duty
Blackmun's dissent stresses that an accountant certifying a broker's financial statements serves the investing public, not only the client. The majority did not deny the importance of audits; it held that the remedy for negligent auditing lies elsewhere than in Section 10(b).
- Why does Blackmun quote the line comparing an accountant's certificate to a chisel or a crowbar?
- What other remedies might investors have against a negligent auditor?
Who should change the law?
Blackmun closed by saying that it rested with Congress to rephrase the statute if investors like the respondents were to recover. The majority, for its part, refused to extend the statute beyond its words. Both opinions thus point to Congress, from opposite directions.
- Why does each side think its reading respects the role of Congress?
- When a court narrows a remedial statute, is the legislature the right place for those who disagree to turn?
Context
Rule 10b-5, adopted by the SEC in 1942, was written for agency enforcement, but from 1946 onward federal courts allowed private investors to sue under it, and the implied private action grew rapidly in the 1960s and early 1970s. Courts of appeals divided over whether such suits required intent, and some allowed recovery for negligence. In Blue Chip Stamps v. Manor Drug Stores (1975) the Burger Court had begun to set limits, holding that only actual purchasers or sellers could sue.
Composition
The Hochfelder suit was filed in 1971 after the SEC's receivership of First Securities. The Seventh Circuit's 1974 decision allowed an aiding-and-abetting claim based on a breach of a duty of inquiry. The Supreme Court granted certiorari in 1975, and the SEC filed an amicus brief supporting the investors on the scienter question.
Reception
The decision became a cornerstone of the law of private securities litigation, and scienter remains an element of every Rule 10b-5 damages claim. Lower courts filled the gap Powell left open by holding that recklessness can satisfy the requirement, and Congress later required plaintiffs to plead facts giving rise to a strong inference of scienter in the Private Securities Litigation Reform Act of 1995. Scholars have debated whether the Court's narrowing of implied remedies respected Congress or curtailed protections Congress intended.
Comparisons
- aaron-v-sec
Four years later the Court extended Hochfelder's scienter rule to SEC injunction suits under Section 10(b), while holding that parts of Section 17(a) of the 1933 Act require no intent.
- united-states-v-ohagan
Justice Ginsburg cited the scienter requirement Hochfelder established as one of the safeguards that keeps the misappropriation theory within proper bounds.
- sec-v-capital-gains-research-bureau
Blackmun's dissent quotes the 1963 case's instruction to read securities laws flexibly rather than technically, the approach Powell declined to follow for Section 10(b).
- tsc-industries-v-northway
Decided in the same term, TSC defined materiality for proxy omissions, another case in which the Court set the elements investors must prove to recover.
Quotes
Frequently cited
“The words "manipulative or deceptive" used in conjunction with "device or contrivance" strongly suggest that § 10(b) was intended to proscribe knowing or intentional misconduct.”
“Thus, despite the broad view of the Rule advanced by the Commission in this case, its scope cannot exceed the power granted the Commission by Congress under § 10(b).”
“When a statute speaks so specifically in terms of manipulation and deception, and of implementing devices and contrivances the commonly understood terminology of intentional wrongdoing and when its history reflects no more expansive intent, we are quite unwilling to extend the scope of the statute to negligent conduct.”
“Perhaps the Court is right, but I doubt it.”
“It seems to me, however, that an investor can be victimized just as much by negligent conduct as by positive deception, and that it is not logical to drive a wedge between the two, saying that Congress clearly intended the one but certainly not the other.”
“The critical importance of the auditing accountant's role in insuring full disclosure cannot be overestimated.”
For Students
A reading companion for classical Christian high school students. See the student guide.
Reading Guide
Watch for
- The respondents' explicit statement that they did not accuse Ernst & Ernst of intentional fraud.
- Powell's discussion of the word manipulative as virtually a term of art.
- The description of Section 10(b) as a catchall clause in the legislative history.
- Powell's comparison with the express negligence remedies of the 1933 Act.
- Blackmun's quotation comparing the accountant's certificate to a chisel or a crowbar.
Key terms and names
- Scienter
- A mental state embracing intent to deceive, manipulate or defraud.
- Rule 10b-5
- SEC rule forbidding fraud, untrue statements and deceptive practices in connection with the purchase or sale of any security.
- Implied private right of action
- A right to sue that courts infer from a statute that does not expressly provide one.
- Aiding and abetting
- Knowingly assisting another person's wrongful act; the respondents claimed the auditors aided Nay's fraud through inaction.
- Negligent nonfeasance
- Careless failure to do something one had a duty to do, here the alleged failure to use proper audit procedures.
- Amicus curiae
- A friend of the court: a non-party, here the SEC, that files a brief offering its view.
Seminar Questions
- Comprehension How did Leston Nay's escrow scheme work, and what was the mail rule?
- Comprehension What three kinds of argument does Powell use to conclude that Section 10(b) requires scienter?
- Interpretation Why does Powell think allowing negligence claims under Section 10(b) would undercut the express remedies Congress wrote into the 1933 Act?
- Interpretation Blackmun says the meaning of a violation should not depend on whether the SEC or a private party sues. How does that point bear on the majority's reasoning?
- Interpretation Why does Powell refuse to send the case back for trial under a stricter standard, and what does that tell you about how the respondents framed their claim?
- Big Question Is it fair for the law to treat a careless professional more leniently than a deliberate deceiver when the investor's loss is the same?
Faith Connections
- Ezekiel 33:6 (Scripture)
The watchman who sees the sword coming and does not blow the trumpet is held accountable, an image of the duty of one charged with watching on behalf of others.
- Luke 12:47-48 (Scripture)
Jesus distinguishes the servant who knew his lord's will and disobeyed from the one who did not know, and says the first shall be beaten with many stripes, a teaching that weighs knowledge in judging fault.
- Aristotle, Nicomachean Ethics, Book III (Great Conversation)
Aristotle distinguishes voluntary acts from those done through ignorance, the moral question underneath the legal debate over scienter.
Logic and Rhetoric
Central argument: Powell argues that the statute's words describe intentional misconduct, that its history describes a catchall against manipulative practices, that Congress expressly limited negligence remedies elsewhere, and that a rule cannot exceed its statute, so negligence is not enough; Blackmun replies that the rule's wording and the investor's injury point the other way.
Rhetorical device: understatement. Blackmun opens his disagreement with a short concession that turns into doubt (quote 3), setting a measured tone for a dissent that ends by calling on Congress.
Debate: Resolved: that an auditor whose negligence allows a client's fraud to continue should be liable to defrauded investors under federal securities law.
Memory Work
The words "manipulative or deceptive" used in conjunction with "device or contrivance" strongly suggest that § 10(b) was intended to proscribe knowing or intentional misconduct.
Perhaps the Court is right, but I doubt it.
Writing Prompts
Essay: Evaluate Powell's reliance on the words manipulative, device and contrivance, and consider whether Blackmun's focus on the investor's injury offers a better guide to the statute's meaning.
Comparison with Aaron v. SEC: Compare how the Court treated scienter in a private damages suit in 1976 and in an SEC injunction suit in 1980, explaining why the Court reached the same answer under Section 10(b) but a different one under parts of Section 17(a).
Medical Lens
A dispute over an accounting firm's liability for a broker's escrow fraud; the opinions concern the mental element of securities fraud in the legal sense and contain no medical subject matter.
Creative Prompts
- Classroom
Hold a moot court in December 1975: counsel for the defrauded customers and the SEC argue that negligence suffices, counsel for Ernst & Ernst argues that the statute's words require intent, and student justices write short opinions modeled on Powell and Blackmun.
- Essay
Write an auditor's memo, as of 1965, explaining why a rule that only the president may open his mail is an irregular practice an audit should report.
- Dialogue
Write a conversation between a First Securities customer who lost savings in the escrow accounts and a lawyer explaining, after March 1976, why the suit against the accountants failed.
- Essay
Explain how Powell uses the word manipulative to build his argument, and evaluate whether the meaning of a single word should carry so much weight in reading a statute.
Further Reading
- Lewis F. Powell, Jr.: A Biography, John C. Jeffries Jr.
Life of the justice who wrote the opinion, including his background in corporate practice and his work on the Burger Court.
- Fundamentals of Securities Regulation, Louis Loss and Joel Seligman
Standard treatise covering Rule 10b-5, implied private actions and the scienter requirement.
- The Transformation of Wall Street: A History of the Securities and Exchange Commission and Modern Corporate Finance, Joel Seligman
History of the SEC that places the growth and narrowing of private securities suits in the agency's development.
Verification notes
All six quotations (three from Powell, three from Blackmun) were confirmed by Grep as exact substrings of content/texts/ernst-and-ernst-v-hochfelder.txt. The stored file's header says notes are omitted, but several of the source's explanatory notes appear after the dissent; the recklessness reservation (note 12 in the U.S. Reports) is not among them and is described from general references. Facts of the escrow scheme, the mail rule and the 1971 filing date come from the stored text. The vote of 6-2 with Stevens not participating is as given in the task.
- Confirm the decision date (30 March 1976) and argument date (December 1975).
- Confirm the full name of the lead respondent, Hochfelder.
- Confirm that Stevens's non-participation was because he joined the Court after argument.