Work record
United States v. O'Hagan
1997 · Postwar Contemporary · Court Decision · English
Abstract
Question Presented. May a person who owes no duty to the shareholders he trades with be convicted of securities fraud for using information confided to his law firm by a client planning a takeover? And may the SEC bar trading on tender-offer secrets without proof that anyone broke a duty?
Arguments. O'Hagan's side contended that fraud under the Exchange Act means deceiving a buyer or seller, which he never did, and that the agency cannot redefine fraud to reach dutiless trading. Federal prosecutors countered that pretending loyalty to Grand Met while quietly exploiting its plans was itself deceit, completed at the moment of purchase, and that a prophylactic disclose-or-abstain rule answers real problems of proof.
Holding. Six justices accepted the government's theory and reversed the Eighth Circuit; seven sustained the tender-offer rule, and the mail fraud counts were reinstated. Thomas, with the Chief Justice, found the line between pilfered information and pilfered cash unprincipled and saw no underlying fraud for the rule to prevent.
Why it matters for advisers. The decision confirmed that anyone entrusted with confidential information, including an adviser or employee who owes a duty to a firm or client, violates Section 10(b) by secretly trading on it. Rule 14e-3(a), upheld here, separately forbids trading on nonpublic tender-offer information regardless of any duty.
Text. Substantial portions of both opinions are included; Scalia's separate writing and the notes are not.
Key figures
- James Herman O'Hagan: Minneapolis law partner who bought Pillsbury options before the Grand Met bid
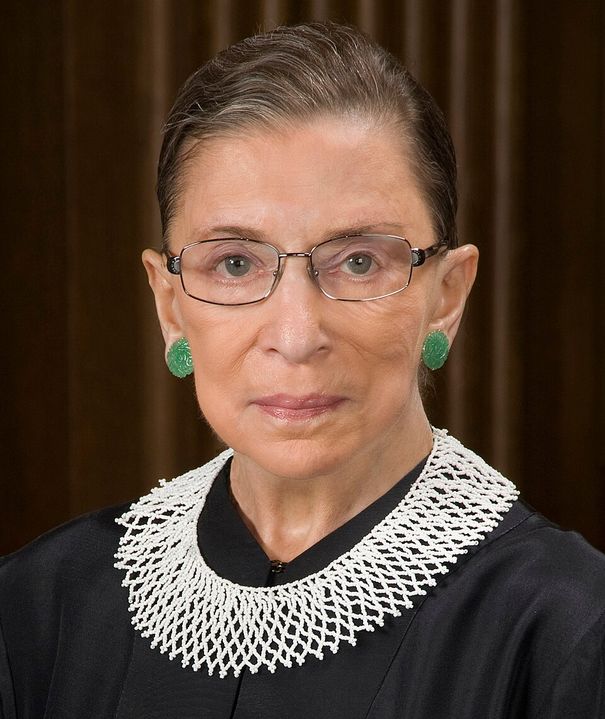
- Ruth Bader Ginsburg: Wrote that feigned fidelity to the source of information is deception
- Clarence Thomas: Partial dissenter, joined by Rehnquist, on both securities holdings
- Antonin Scalia: Dissented from the Section 10(b) holding in a separate opinion
- Grand Metropolitan PLC: Bidder whose confidential plans were misused

Summary
James Herman O'Hagan was a partner in the Minneapolis law firm Dorsey & Whitney. In July 1988 the London company Grand Metropolitan PLC retained the firm as local counsel for a possible tender offer for the Pillsbury Company. O'Hagan did no work on the matter, but beginning in August 1988, while the firm still represented Grand Met, he bought Pillsbury call options and about 5,000 shares of stock. When Grand Met announced its offer on 4 October 1988, Pillsbury shares rose from just under $39 to nearly $60, and O'Hagan sold for a profit of more than $4.3 million. The government charged that he used the gains to cover earlier thefts from client trust funds. A jury convicted him on all 57 counts, including securities fraud, fraudulent trading in connection with a tender offer, mail fraud and money laundering, and he received a 41-month sentence. A divided Eighth Circuit panel reversed every conviction. Two main questions reached the Court. Was a trader who misused confidential information belonging to his firm and its client, rather than to the company whose shares he bought, guilty of fraud under Section 10(b) of the Securities Exchange Act and Rule 10b-5? And did the Securities and Exchange Commission exceed its authority in Rule 14e-3(a), which forbids trading on undisclosed tender-offer information whether or not any fiduciary duty is breached? O'Hagan argued that he owed no duty to the Pillsbury shareholders who sold to him, so he deceived no one in the market, and that a rule reaching trades without any breach of duty went beyond the fraud Congress had authorized the SEC to define. The government answered that he had deceived the source of the information by feigning loyalty while secretly using it, and that the rule was a reasonable means of preventing fraud that is hard to prove. The Court reversed. Justice Ginsburg's opinion adopted the misappropriation theory: a fiduciary who trades on a principal's confidential information without disclosure defrauds the principal, and the fraud is consummated in the trade itself. Six justices agreed on that point; Justice Scalia, in a separate opinion not in the library text, and Justice Thomas, joined by Chief Justice Rehnquist, did not. By 7-2 the Court also upheld Rule 14e-3(a) as a means reasonably designed to prevent fraud in tender offers, and it held that the mail fraud counts did not depend on the securities counts. Justice Thomas agreed on mail fraud but argued that the government's own distinction between misusing information and embezzling money showed the theory had no coherent account of the statutory phrase in connection with. The library text gives substantial excerpts from the Ginsburg and Thomas opinions, without footnotes. On remand the Eighth Circuit upheld the convictions in 1998. In 2000 the SEC adopted Rule 10b5-2, listing relationships, including some family relationships, that create a duty of trust or confidence for misappropriation cases.
Virtues in this work
- Justice: Ginsburg holds that a fiduciary who secretly turns a principal's information to his own profit takes what belongs to another.
- Honor: The theory rests on fidelity: a lawyer's loyalty to his firm and its client is the duty O'Hagan was found to have betrayed.
- Prudence: Thomas insists that a theory of criminal liability state its limits consistently before courts apply it to a defendant.
Plot or Argument
- A partner, a client and a tender offer
Ginsburg recounts how O'Hagan, whose firm advised Grand Met, bought Pillsbury options and shares before the October 1988 announcement, the 57 criminal counts filed against him, and the Eighth Circuit's reversal of all convictions.
- Classical and misappropriation theories
Section 10(b) and Rule 10b-5 forbid deceptive devices in connection with securities trades. The classical theory reaches insiders who trade with their own shareholders; the misappropriation theory reaches outsiders who deceive the source of confidential information. The opinion calls the two complementary.
- Deception of the source, consummated in the trade
Undisclosed use of a principal's information is fraud akin to embezzlement. Because deception lies in feigning fidelity, full disclosure to the source removes Section 10(b) liability, and the fraud is completed when the information is used to buy or sell securities.
- Chiarella, Dirks and Central Bank distinguished
The Court reads Chiarella as having left the misappropriation theory open, finds room for it in Dirks, and limits Central Bank to private aiding-and-abetting suits, adding that the statute's scienter requirements guard against unfair criminal liability.
- Rule 14e-3(a) and the Williams Act
Section 14(e) lets the SEC prescribe means reasonably designed to prevent fraud in tender offers. A disclose-or-abstain rule that does not require proof of a breached duty is upheld as a reasonable answer to the difficulty of proving how traders obtained their information.
- Mail fraud
Following Carpenter v. United States (1987), the Court holds that the mail fraud counts stand independently of the securities counts and remands O'Hagan's remaining challenges.
- Thomas's partial dissent (excerpt)
Thomas accepts that undisclosed misappropriation can be deceptive but argues that information, like money, has uses other than trading, so the government's attempt to cover one and exclude the other leaves the in-connection-with requirement without a consistent meaning; he also finds no underlying fraud that Rule 14e-3(a) prevents.
Characters
- James Herman O'Hagan, respondent
Dorsey & Whitney partner who traded Pillsbury securities while his firm represented the bidder, Grand Met.
- Justice Ruth Bader Ginsburg, author of the opinion of the Court
Wrote that trading on a principal's confidential information while feigning loyalty is securities fraud.
- Justice Clarence Thomas, concurring in the judgment in part and dissenting in part
Argued the misappropriation theory lacked a coherent reading of the in-connection-with requirement and that Rule 14e-3(a) exceeded the SEC's power.
- Chief Justice William H. Rehnquist, joined the Thomas opinion
Joined Thomas in dissent from both the Section 10(b) and Rule 14e-3(a) holdings.
- Justice Antonin Scalia, concurring in part and dissenting in part
Wrote separately, outside the library text, against the Section 10(b) holding while joining the rest of the Court's opinion.
- Grand Metropolitan PLC, client of Dorsey & Whitney
London-based company whose confidential tender-offer plans for Pillsbury were the information O'Hagan used.
Lessons
Fraud on the source of information
The misappropriation theory locates the deception not in the market but in the relationship of trust between the trader and the person who entrusted him with information. O'Hagan owed nothing to the Pillsbury sellers, but he owed loyalty and confidentiality to his firm and its client, and his secret use of their information was the fraud.
- Whom did O'Hagan deceive, according to Ginsburg's opinion?
- Why does the Court compare the misuse of confidential information to embezzlement?
- Should the law treat information as property in the same way it treats money?
Disclosure as the dividing line
Because the theory rests on feigned fidelity, the Court said a fiduciary who tells the source he plans to trade commits no Section 10(b) deception, though he may still breach duties under state law. The holding shows how securities law turns on candor within a relationship rather than on fairness in the abstract.
- What would have changed in the Section 10(b) analysis if O'Hagan had told Dorsey & Whitney and Grand Met of his plans?
- Why does the Court still mention liability under state law?
- Is a rule that turns on disclosure to one party enough to protect other investors?
Defining a statutory phrase
Thomas's partial dissent presses on the words in connection with. If misused information is covered because its only value lies in trading, he asks, why not money embezzled to buy stock, and what of information that could also be sold to a newspaper? The exchange shows how a court tests a theory against its own stated limits.
- What examples does Thomas give of other uses O'Hagan could have made of the information?
- How does Ginsburg respond to the charge that the theory is incoherent?
- When a statute's words are general, how precise should a court require a theory of liability to be?
Rules that prevent as well as punish
In upholding Rule 14e-3(a), the Court accepted that an agency may forbid some conduct that is not itself fraud in order to prevent fraud that is hard to prove. The SEC pointed to the wide circle of people who learn of tender offers and the difficulty of tracing a tip to a breach of duty.
- What proof problem did the SEC say Rule 14e-3(a) solves?
- Why did Thomas think the rule lacked an underlying fraud to prevent?
Context
Federal insider-trading law grew from Section 10(b) of the Securities Exchange Act of 1934 and the SEC's Rule 10b-5, adopted in 1942. In Chiarella (1980) and Dirks (1983) the Court tied liability to a duty arising from a relationship of trust, and Chief Justice Burger's Chiarella dissent proposed the misappropriation theory. The takeover wave of the 1980s, with large premiums paid for target shares, made advance knowledge of tender offers especially valuable.
Composition
Lower courts divided over the misappropriation theory for more than a decade; the Second Circuit accepted it, and the Fourth and Eighth Circuits rejected it. In Carpenter v. United States (1987) the justices split 4-4 on the theory under Section 10(b) while unanimously upholding mail fraud convictions. O'Hagan was argued on 16 April 1997 and decided on 25 June 1997.
Reception
The decision settled the theory as a basis for criminal and SEC enforcement, and the Commission's Rule 10b5-2 (2000) spelled out when family and confidential relationships create the necessary duty. Commentators have debated whether the theory protects market integrity or chiefly protects the property interests of information owners, a question that Thomas's opinion sharpened by asking what makes misused information different from misused money.
Comparisons
- chiarella-v-united-states
Chiarella refused to impose a general duty to disclose on a printer who decoded takeover targets, while Burger's dissent there proposed the misappropriation theory that O'Hagan adopted seventeen years later.
- dirks-v-sec
Dirks tied tippee liability to an insider's breach of duty; O'Hagan relied on its reasoning to show that a duty owed to the source of information, not to shareholders, could also ground liability.
- ernst-and-ernst-v-hochfelder
Hochfelder's holding that Section 10(b) requires scienter is one of the safeguards Ginsburg cites in answer to the worry that the misappropriation theory reaches too far.
- sec-v-capital-gains-research-bureau
Both cases treat a fiduciary's undisclosed self-interest as a form of fraud, the 1963 case for an investment adviser's own trades ahead of his recommendations.
Quotes
Frequently cited
“Under this theory, a fiduciary's undisclosed, self-serving use of a principal's information to purchase or sell securities, in breach of a duty of loyalty and confidentiality, defrauds the principal of the exclusive use of that information.”
“Because the deception essential to the misappropriation theory involves feigning fidelity to the source of information, if the fiduciary discloses to the source that he plans to trade on the nonpublic information, there is no "deceptive device'' and thus no §10(b) violation-although the fiduciary-turned-trader may remain liable under state law for breach of a duty of loyalty.”
“The theory is also well-tuned to an animating purpose of the Exchange Act: to insure honest securities markets and thereby promote investor confidence.”
“Although informational disparity is inevitable in the securities markets, investors likely would hesitate to venture their capital in a market where trading based on misappropriated nonpublic information is unchecked by law.”
“it makes scant sense to hold a lawyer like O'Hagan a §10(b) violator if he works for a law firm representing the target of a tender offer, but not if he works for a law firm representing the bidder.”
“Because the Commission's misappropriation theory fails to provide a coherent and consistent interpretation of this essential requirement for liability under §10(b), I dissent.”
For Students
A reading companion for classical Christian high school students. See the student guide.
Reading Guide
Watch for
- The two prime questions Ginsburg lists in her first paragraph.
- The contrast between the classical theory and the misappropriation theory.
- Ginsburg's statement that full disclosure to the source forecloses Section 10(b) liability.
- The two sturdy safeguards regarding scienter that the Court emphasizes.
- Thomas's list of things O'Hagan could have done with the information besides trading.
Key terms and names
- Misappropriation theory
- The view that a person commits securities fraud by trading on confidential information in breach of a duty owed to the source of that information.
- Fiduciary
- A person, such as a lawyer or trustee, bound to act with loyalty and confidentiality for another.
- Tender offer
- A public offer to buy shares of a company from its shareholders, usually at a premium, in order to gain control.
- Call option
- A contract giving the holder the right to buy shares at a set price before a set date.
- Rule 14e-3(a)
- SEC rule requiring anyone holding material nonpublic information about a pending tender offer from the bidder or target to disclose it or abstain from trading.
- Scienter
- A mental state embracing intent to deceive, manipulate or defraud; in criminal cases the statute required willful violation.
Seminar Questions
- Comprehension What did O'Hagan buy, when did he buy it, and how did his firm's work for Grand Met give him the information?
- Comprehension What two main questions does Ginsburg say the case presents, and how does the Court answer each?
- Interpretation Why does the Court say the fraud is consummated at the moment of the trade rather than when O'Hagan learned the information?
- Interpretation How does Thomas use the government's own example of embezzled money to challenge the theory?
- Interpretation Why does Ginsburg think it would be arbitrary to punish a lawyer for the target but not a lawyer for the bidder?
- Big Question Is the wrong in insider trading chiefly a wrong to other investors, to the owner of the information, or to the fairness of markets as a whole?
Faith Connections
- Luke 16:10-12 (Scripture)
Jesus teaches that one faithful in little is faithful in much, and asks who will give you what is your own if you have not been faithful in that which is another man's, words that bear on a steward's use of entrusted knowledge.
- Proverbs 11:1 (Scripture)
A false balance is abomination to the Lord, but a just weight is his delight, a proverb about honest dealing in trade.
- Cicero, De Officiis, Book III (Great Conversation)
Cicero asks whether a grain merchant who knows more ships are coming must tell buyers, an ancient debate over how much a trader owes others about what he knows.
Logic and Rhetoric
Central argument: Ginsburg reasons that Section 10(b) forbids deceptive devices used in connection with securities trades, that secretly using a principal's information while feigning loyalty is deception of the principal, and that the deception is completed in the trade itself; Thomas replies that the government's line between information and money shows the theory has no consistent account of the connection required.
Rhetorical device: reductio by hypothetical. Thomas imagines O'Hagan selling the news to a newspaper or using it in a fantasy stock game to show that information, like money, has uses besides trading, while Ginsburg uses the target-versus-bidder lawyer to show the absurdity of the opposite rule (quote 4).
Debate: Resolved: that trading on information entrusted to one's employer or client should be a federal securities crime even when the trader owes no duty to the other side of the trade.
Memory Work
Under this theory, a fiduciary's undisclosed, self-serving use of a principal's information to purchase or sell securities, in breach of a duty of loyalty and confidentiality, defrauds the principal of the exclusive use of that information.
The theory is also well-tuned to an animating purpose of the Exchange Act: to insure honest securities markets and thereby promote investor confidence.
Writing Prompts
Essay: Explain the misappropriation theory as Ginsburg defines it, then evaluate Thomas's objection that it cannot distinguish misused information from embezzled money.
Comparison with Chiarella v. United States: Compare the printer in Chiarella with the lawyer in O'Hagan: both traded on advance knowledge of takeovers, so explain why the Court reversed one conviction and reinstated the other.
Medical Lens
A securities-fraud prosecution about a lawyer's trading on a client's tender-offer plans; the opinions raise no question of medicine or health.
Creative Prompts
- Classroom
Stage the April 1997 argument: one student argues for the United States that O'Hagan deceived Grand Met, another argues for O'Hagan that he deceived no one he traded with, and student justices must decide each of the two main questions separately.
- Essay
Write a one-page compliance memo for a fictional law firm explaining, in plain terms, why the Court said a partner who never worked on a deal could still misuse what the firm knew.
- Dialogue
Write the conversation Justice Thomas imagines: O'Hagan deciding among selling the news to a newspaper, telling Pillsbury, keeping it for a fantasy trading game, or trading on it. Have a lawyer explain which choices the misappropriation theory reaches.
- Essay
Trace the misappropriation theory from Burger's dissent in Chiarella (1980) through Carpenter (1987) to O'Hagan (1997), showing how a dissenting idea became the law.
Further Reading
- Insider Trading Law and Policy, Stephen M. Bainbridge
Law-school text explaining the classical and misappropriation theories and the policy debate over insider trading.
- Den of Thieves, James B. Stewart
Journalist's account of the 1980s insider-trading scandals that shaped enforcement during the takeover era in which O'Hagan traded.
- The Transformation of Wall Street: A History of the Securities and Exchange Commission and Modern Corporate Finance, Joel Seligman
Institutional history of the SEC, including its development of Rule 10b-5 enforcement.
Verification notes
All six quotations (five from Ginsburg, one from Thomas) were found by Grep as exact substrings of content/texts/united-states-v-ohagan.txt, keeping the source's doubled-apostrophe closing quotation marks and hyphens. Facts about the trades, the $4.3 million profit, the number of counts, the 41-month sentence and the trust-fund allegation come from the stored opinion. The vote (6-3 on Section 10(b), 7-2 on Rule 14e-3(a)) is as given in the task and agrees with the standard account that Scalia dissented from the Section 10(b) holding only; his opinion is not in the library text. The remand outcome and Rule 10b5-2 are from general references.
- Confirm the vote breakdown (6-3 on Section 10(b), 7-2 on Rule 14e-3(a)) against the U.S. Reports syllabus.
- Confirm that the Eighth Circuit affirmed the convictions on remand in 1998 (139 F.3d 641).
- Confirm the argument date of 16 April 1997.